Entry in Non-Standard Auto Insurers Explained
What to Do When Auto Insurers Decline Your Application
Learn why auto insurers reject applications, how non-standard carriers differ from assigned-risk plans, and the steps to secure coverage when declined.
By Gabriel Ortiz · Editor
Published
Answer in brief
Being turned down by an auto insurer means your driving record, credit-based insurance score, or loss history placed you outside that company's underwriting guidelines. You still have viable options: specialty non-standard insurers write policies for elevated-risk profiles, and state assigned-risk plans guarantee an avenue for mandatory financial responsibility. Reviewing your record, gathering key vehicle information, and comparing non-standard quotes can help you secure legal coverage.
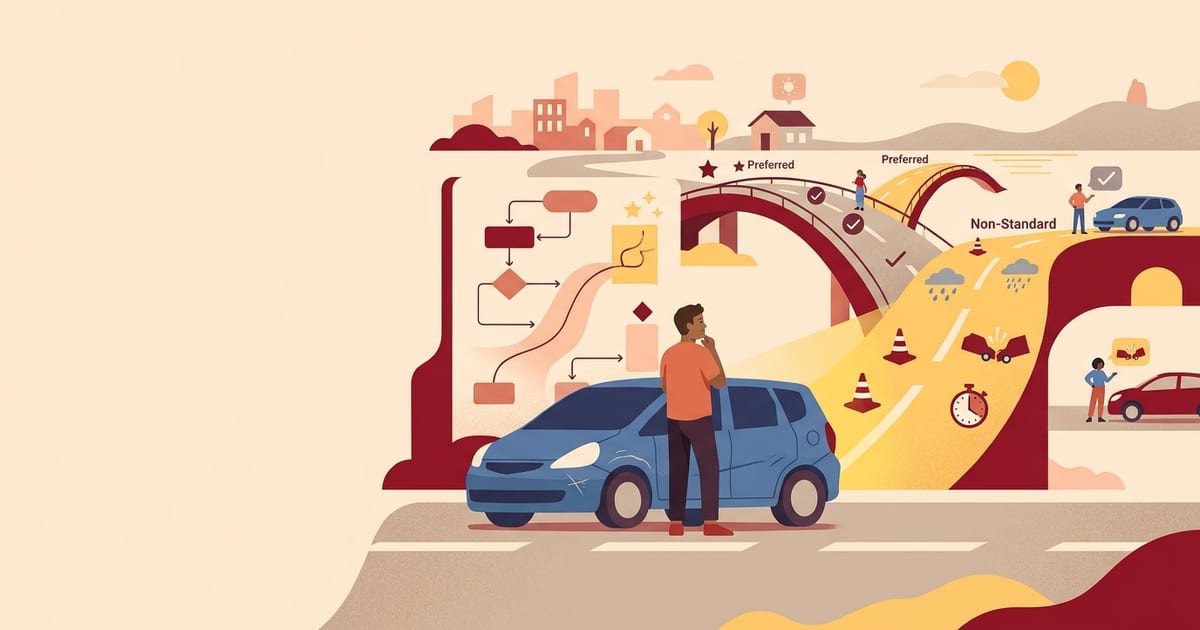
Receiving a denial letter from an auto insurer can feel alarming, especially when state law mandates continuous coverage to drive legally. However, a denial simply means your specific risk profile falls outside that carrier's voluntary underwriting appetite. Standard and preferred carriers routinely reject applicants who have recent moving violations, at-fault accidents, lapses, or poor credit-based insurance scores.
Every state requires motorists to maintain proof of financial responsibility before operating a vehicle on public roads. When mainstream carriers decline to issue a policy, drivers must turn to alternative markets—specifically private non-standard insurance carriers or state-sponsored residual market plans.
Common Reasons Insurers Decline Coverage
Carriers evaluate prospective policyholders using actuarial models designed to predict claim frequency and severity. When a driver's composite risk exceeds the threshold established for a specific rating tier, the application is declined rather than merely surcharged.
The Voluntary Non-Standard Market vs. Assigned-Risk Plans
When the standard market turns you away, there are two distinct tiers of protection available: private non-standard carriers and residual assigned-risk pools.
| Feature | Non-Standard Private Insurers | State Assigned-Risk Plans |
|---|---|---|
| Market Type | Competitive voluntary market | Residual / shared market of last resort |
| Availability | Specialty licensed insurers nationwide | Available through state-designated mechanisms |
| Pricing | High, but competitive between competing carriers | Typically the most expensive pricing tier available |
| Coverage Options | State minimums plus optional collision and comprehensive | Often limited to compulsory statutory liability limits |
| Filing Support | Routine issuance of SR-22 certificates | Handles statutory filings for license restoration |
In the private non-standard sector, companies specialize exclusively in higher-risk profiles. These insurers accept drivers with multiple points, recent license suspensions, or an SR-22 filing requirement. Because multiple private companies compete in this space, premium pricing can vary widely between carriers for the exact same motorist.
Steps to Take Immediately After Being Declined
Driving without coverage can lead to vehicle impoundment, fines, and license suspension. If your application has been rejected, follow this structured process to get back on the road with valid insurance.
- 1
Review the Adverse Action Notice
Underwriters must provide a specific rationale for rejecting an application. Check whether the denial was based on motor vehicle records, claims history reports, or a credit-based insurance score.
- 2
Verify Driving and Claims Records for Errors
Request a copy of your motor vehicle record from your state licensing agency. Ensure resolved tickets or erroneous citations are not misreported.
- 3
Seek Quotes from Non-Standard Specialists
Approach carriers that write high-risk drivers. Using an independent quote comparison tool lets you reach insurers that look beyond standard tier guidelines.
- 4
Explore Assigned-Risk Facilities as a Last Resort
If every private carrier refuses coverage, contact an agent certified to submit an application through your state's assigned-risk or shared-market plan to satisfy legal financial responsibility.
Managing Premiums in the High-Risk Market
According to the National Association of Insurance Commissioners (NAIC), the countrywide average expenditure for auto insurance was $1,281 in 2023. Drivers entering the non-standard market typically face higher costs due to surcharges for prior violations, accidents, or lapses.
To keep non-standard costs manageable, consider adjusting coverage structures. Research from the Insurance Information Institute indicates that increasing your physical damage deductible from $200 to $500 can lower collision and comprehensive costs by 15% to 30%, while choosing a $1,000 deductible can cut those specific costs by 40% or more. On older vehicles valued at less than ten times the annual physical damage premium, dropping optional collision and comprehensive coverage altogether may significantly lower your total policy expenditure.
Questions & answers
Can an auto insurer deny my application without giving a reason?
No. When an insurer declines an application, state insurance regulations and fair credit reporting rules require the company to provide written notice explaining the adverse action and identifying the records used to make the decision.
What is an assigned-risk plan in car insurance?
An assigned-risk plan (or shared market) is a state-mandated program that assigns drivers who are unable to obtain insurance in the voluntary market to licensed auto insurers in proportion to each carrier's market share.
How long will I have to remain in the non-standard market?
Most insurers use lookback periods of three to five years for violations and accidents. Maintaining continuous coverage without new incidents allows your profile to transition back to standard rating tiers as older surcharges expire.
Terms: High-risk driver, Non-standard insurance, Financial responsibility, Deductible, SR-22
Sources and references
Legal figures on this page (minimum limits, filing periods, statutory benefits) are checked against the primary law or the state insurance regulator listed below. Links and figures last verified Nov 2026.
- 2019–2023 Auto Insurance Database: average premium supplement — National Association of Insurance Commissioners (2025)Statistical dataCountrywide average expenditure $1,281 in 2023 (+13.98%); combined average premium $1,438; state tables for liability, collision and comprehensive.
- What if I can't find auto coverage? — Insurance Information InstituteConsumer guidanceHow the non-standard market and state assigned-risk plans insure drivers the voluntary market declines.
- Is it legal to drive without insurance? — Insurance Information InstituteConsumer guidanceEvery state requires drivers to demonstrate financial responsibility; in most states insurance is the mandatory way to do so.
- Nine ways to lower your auto insurance costs — Insurance Information InstituteConsumer guidanceShop at least three quotes; raising a deductible from $200 to $500 can cut collision/comprehensive cost 15–30%, $1,000 can save 40%+; drop physical damage on cars worth under 10× the premium; bundling, low-mileage and good-student discounts.
- What determines the price of an auto insurance policy? — Insurance Information InstituteConsumer guidanceRating factors: driving record, mileage, location, age, gender, vehicle, credit-based insurance score, coverage choices. Notes ZIP-code rating is prohibited in California and Michigan and gender rating is prohibited in seven states.
Practical guidance on this page is original editorial work. Cited sources support factual statements and do not endorse this site. Dollar ranges described as typical or illustrative are editorial estimates, not figures from these sources.